

Skrill - Fast, secure payments
4.5

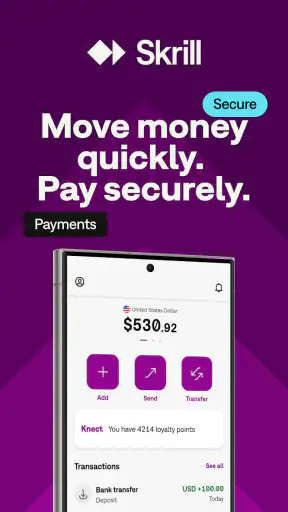
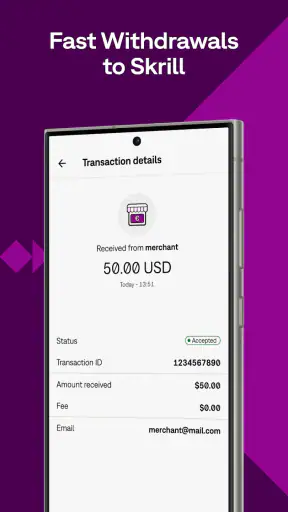
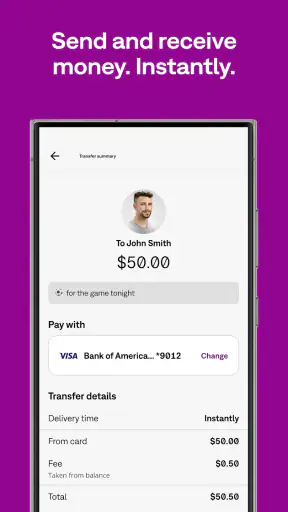
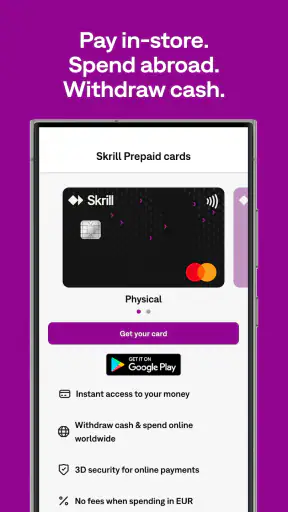
I use mobile finance apps for one simple reason: I want a payment task to take less effort than opening a laptop or visiting a branch. Skrill fits that role as a free finance app built around sending and managing money from a phone. After spending time with it, I found the experience most useful for people who already need a digital wallet for transfers, online payments, or moving money between supported services. It is less convincing as a universal replacement for a bank account, especially if you expect every transaction to be free or every country and payment method to work in exactly the same way.
Skrill is developed by Paysafe Holdings UK Limited and is available for everyone in its stated age category. It has been around since September 2014, so this is not a new experiment trying to establish itself overnight. Its current Android version is 3.191.0-2026081013, and it requires Android 8.0 or later. The app has reached over ten million installs, with a 4.5 average from around 239 thousand ratings and roughly four thousand written reviews. Those figures do not replace personal testing, but they do show that the service has a substantial mobile user base.
What Skrill is really useful for on a phone
The store summary presents a straightforward idea: transfer money with your phone. In practice, the appeal is the wallet-style workflow. Rather than treating the app as a traditional banking application with a full branch of services, I see it as a convenient middle layer between your phone, your payment sources, and the people or businesses you need to pay. That distinction matters because it sets a more realistic expectation from the beginning.
The strongest use case is a person who regularly handles digital payments and wants one place to start them. For example, imagine receiving a message from a friend who needs their share of a household purchase while you are away from your computer. A phone-based wallet can be quicker than logging into online banking, finding the correct recipient, and repeating the process later. Skrill is also relevant when the recipient or merchant already uses Skrill, because a shared platform can reduce the awkwardness of deciding which payment route both people support.
I would not describe it as a magic shortcut for every financial situation. A wallet can make a transfer feel simple while the underlying transaction still depends on the funding method, destination, currency, verification steps, or applicable charges. The cleanest experience comes when you know exactly where the money is coming from, who is receiving it, and whether both sides are using compatible payment arrangements.
Free access is useful, but it is not the same as free transactions
Skrill is free to download and use as an app, which gives it an easy entry point. You can install it without committing to a purchase, explore the interface, and decide whether its workflow suits your needs. That is meaningful value for anyone comparing finance tools, because you are not paying upfront simply to discover that the app does not fit your habits.
Still, I would separate free app access from the cost of individual financial actions. The fact that the app itself is free does not automatically mean that every transfer, funding method, withdrawal, currency conversion, or other service carries no charge. Costs can depend on the route you choose and the details of the transaction. Before confirming an important payment, I would always inspect the final screen carefully rather than assuming that “free” describes the entire money movement.
That habit is especially important for international use. Currency conversion can change the value received, and a payment that looks small in the original currency may become less attractive after exchange-related costs or other applicable charges. Skrill can still be worthwhile when speed and convenience matter more than finding the absolute lowest possible cost, but people who move money across borders frequently should compare the complete amount received, not just the headline transfer amount.
The everyday workflow I found most practical
My preferred way to use a wallet app is to prepare before I need it. I would install Skrill, complete the account and security steps carefully, and make sure the intended funding source is available before trying to send money under time pressure. This avoids the common mistake of treating a financial app like a casual messaging tool. The recipient's details deserve the same attention as the amount.
A realistic scenario is splitting a recurring expense with a friend who does not want to exchange bank details. I would open the app, choose the relevant transfer path, check the recipient information, review any displayed cost or conversion, and only then confirm. The useful insight is that the review screen is not a formality: it is where I would look for the final amount leaving my balance and the amount expected to arrive. Taking a few seconds there is more valuable than trying to fix an incorrect transfer afterward.
For regular payments, I would keep a small record outside the app as well. A wallet can show activity, but a separate note or monthly budget makes it easier to notice repeated charges, forgotten subscriptions, or transfers that looked insignificant individually. Skrill can simplify the action of paying; it does not replace the discipline of tracking why the money was sent.
Where the app delivers value beyond the basic transfer idea
The first useful advantage is mobility. A phone-based payment tool is available during the moments when a desktop banking session feels excessive. That makes it practical for small, time-sensitive payments and for users who conduct much of their financial life from a smartphone. The benefit is not merely that the app exists on mobile; it is that the payment decision and the payment action can happen in the same place.
The second advantage is separation. Some people prefer not to give every merchant or contact direct access to their primary bank details. A digital wallet can provide an intermediate account structure, although I would still treat it as a serious financial account and protect it accordingly. This separation is most useful when it matches the recipient's or merchant's accepted payment method. If the other side only wants a bank transfer or cash, the wallet may add an unnecessary step rather than remove one.
The third advantage is convenience for users who already have a Skrill-based payment routine. Once your contacts, merchants, and personal habits align around the service, the value comes from reducing repeated setup. That is a network effect rather than a feature I would recommend in isolation: the app becomes more useful when the people and services you pay are already compatible with it.
I also appreciate that the app belongs to the finance category rather than pretending to be a complete personal-finance coach. I would use it for movement and handling of money, not expect it to teach me how to budget, invest, or build a long-term financial plan. Keeping that boundary clear prevents disappointment and helps explain why another specialist app may be better for budgeting or expense analysis.
The tradeoffs I would consider before relying on it
The biggest tradeoff is convenience versus cost visibility. A fast transfer is valuable, but a fast button can encourage people to confirm before they understand the total. I would not send a large amount until I had checked the displayed details, the destination, and the funding source. This is particularly important when currencies or international recipients are involved.
Another limitation is dependence on the surrounding payment ecosystem. Skrill cannot make an unsupported recipient, merchant, card, or bank route compatible. If the person you need to pay does not use the service or cannot receive money through your chosen method, you may end up transferring funds into the wallet and then moving them again. In that situation, a direct bank transfer or another payment app may be simpler.
There is also a practical security tradeoff. Putting payment capability in your pocket is convenient, but it means your phone and account deserve careful protection. I would use a strong device lock, avoid sharing account credentials, and pause before approving unexpected requests. I would also verify recipient details through a separate conversation when a payment request arrives suddenly. These are not Skrill-specific tricks; they are essential habits whenever a phone can authorize money movement.
Account access and verification can also create friction at the least convenient time. Financial services may need identity or transaction checks, and a user who has never prepared the account could be delayed when trying to make an urgent payment. My practical advice is to set up the account well before a deadline, not while standing at a checkout or waiting for a transfer to arrive.
How it compares with ordinary alternatives
Compared with a normal bank app, Skrill feels more focused on wallet-style payments and less like the central home for every banking relationship. A bank app is usually the natural choice when you need salary management, account balances, direct debits, or a transfer to someone who expects conventional banking details. Skrill is more attractive when the payment context already points toward a digital wallet and you value a mobile-first route.
Compared with cash, the app is easier for remote payments and leaves a digital trail that can help with personal records. Cash remains simpler for face-to-face exchanges where both people are present and no account setup is needed. If your main goal is to hand someone a small amount immediately without either person wanting a digital account, Skrill is not automatically the better answer.
Compared with card payments, the wallet can be useful when the recipient or service specifically supports Skrill. A card is often more universal at ordinary shops, while a wallet can be more convenient within its own network. I would choose based on acceptance and total cost, not on the assumption that one payment method is always superior.
Compared with other digital wallets, the deciding factor is usually where your contacts already are and which funding or withdrawal routes suit your country. Switching between wallets can create extra balances, extra verification, and extra opportunities to overlook a fee. If your existing wallet handles the same payments smoothly and at a lower total cost, there is little reason to move just because Skrill is free to install.
Who is likely to get the most value?
I think Skrill is a good fit for people who make digital transfers from a phone, pay contacts or merchants that already accept it, and want to try a wallet without an upfront app price. It can also suit users who prefer keeping certain payment activity separate from their main banking app. The value becomes stronger when convenience, mobile access, and recipient compatibility matter more than having every financial service in one place.
It is less suitable for someone who only makes occasional local payments and already has a reliable bank app. In that case, adding another account may create more administration than benefit. I would also hesitate to recommend it as the only tool for someone who needs detailed budgeting, broad banking services, or a guaranteed low-cost route for every international transfer.
Families should think about account ownership and responsibility before using any wallet for shared expenses. I would not casually let another person use my logged-in account or phone. Instead, each person should understand who is sending the money, who controls the account, and how records will be kept. The app may simplify payment, but it does not remove the need for clear household rules.
My verdict after weighing the free entry against the real tradeoffs
Skrill earns a recommendation when you have a concrete wallet use case rather than a vague hope that it will improve all of your finances. Its free access makes trying it low-risk from a purchase perspective, and its long presence, large install base, and strong average rating make it a credible option to investigate. The practical value lies in making compatible digital payments from a phone with less friction than a desktop-based routine.
My recommendation comes with one condition: treat every confirmation screen as a cost and accuracy check. The app is not automatically the cheapest route simply because downloading it costs nothing. For a small, familiar payment to a compatible recipient, that distinction may be acceptable. For repeated international transfers, large amounts, or transactions where the recipient's method is uncertain, I would compare the final received amount with a bank or another wallet before choosing.
My buy-or-skip verdict is simple: try Skrill if mobile wallet transfers match your real routine, but skip it if your bank app already solves your needs or you require a universally accepted, consistently low-cost payment route. Since there is no upfront app price, testing the workflow is easy; deciding whether to keep using it should depend on recipient compatibility, visible transaction costs, and how much convenience you genuinely gain.
4.5
3.97K Reviews
Pros
- Fast transfers to supported banks and digital wallets
- Available in many countries and multiple currencies
- Useful for online shopping and international payments
- Strong account security with PIN and verification options
- Clear transaction history helps track spending
Cons
- Fees can vary significantly by transaction type and region
- Currency conversion rates may include an additional markup
- Identity verification can take time for some users
- Some merchants may not accept Skrill payments
- Accounts may face temporary limits during security checks


